Lifelong Security
for the Child You Love.
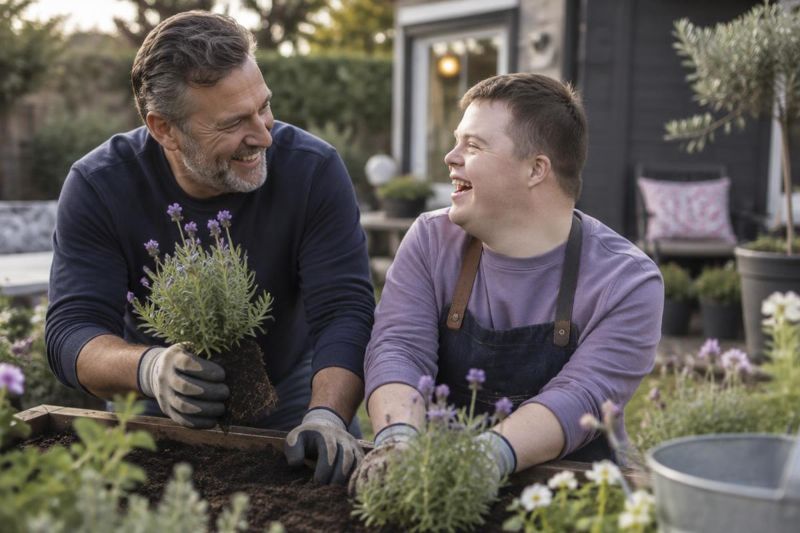
Plan for your child’s future without putting the benefits they rely on at risk — now, at 18, and long after you’re gone.
Questions Parents Ask Us
- “Who will care for my child when I can’t?”
- “Will an inheritance cause my child to lose benefits?”
- “What changes legally when my child turns 18?”
- “Should grandparents leave money to my child directly?”
- “What is an ABLE account, and do we need one?”
- “How do I write down everything a future caregiver needs to know?”
“I don’t want to leave a mess for my kids. I want to leave a legacy of security, not stress.”What we hear from families
What We Help You Put in Place
Special Needs Trusts
Hold money for your loved one’s extra needs without counting against needs-based benefits.
Benefits-Smart Planning
Coordinate your will, trust, and beneficiary designations so gifts don’t backfire.
Planning for Age 18
Decide what support your child needs as an adult — from powers of attorney to guardianship.
ABLE Accounts
Understand how an ABLE account can fit alongside a trust.
Family Coordination
Help grandparents and relatives give in a way that protects your child.
Letter of Intent
Capture routines, care needs and wishes for future caregivers.
Part of One Clear Blueprint
The Strategic Legacy Blueprint Session
Special needs planning touches every part of your family plan — your will, your trust, even what grandparents leave behind. The Blueprint Session pulls it all into one coordinated plan.
Common Questions
What is a special needs trust?
It’s a trust that holds money for a person with a disability to pay for extra needs, while generally keeping that money from counting against needs-based benefits like SSI and Medicaid when it’s set up and managed correctly.
Can grandparents leave money directly to my child?
A direct gift or inheritance can put needs-based benefits at risk. Often a better path is leaving it to a special needs trust. We can help coordinate the whole family’s plans.
What happens legally when my child turns 18?
At 18, your child is legally an adult, and parents no longer automatically make medical or financial decisions for them. Depending on your child’s needs, options range from powers of attorney to guardianship.
What is an ABLE account?
An ABLE account is a tax-advantaged savings account for some people with disabilities. It can work alongside a special needs trust. Whether it fits depends on your family’s situation.
More questions about special needs planning (5)
What is the difference between a first-party and a third-party special needs trust?
A third-party trust holds money from parents, grandparents, or others for the person with a disability. A first-party trust holds the person’s own money, such as an inheritance or settlement, and usually must pay back Medicaid after the person passes away. The right choice depends on whose money is going into the trust.
What is Georgia STABLE?
Georgia STABLE is Georgia’s ABLE program — tax-advantaged savings accounts for eligible people with disabilities. An ABLE account can often be used alongside a special needs trust.
Who should serve as trustee of a special needs trust?
Someone organized, trustworthy, and willing to learn the benefit rules — because the way money is spent matters. Some families choose a relative, others a professional trustee, and some use both.
Should I leave my child with special needs out of my will?
Not necessarily. Instead of leaving nothing, many families leave that child’s share to a special needs trust. That way your child still benefits, without putting needs-based benefits at risk.
What is a letter of intent?
It’s a non-legal document that tells future caregivers about your loved one’s routines, medical needs, preferences, and what makes them happy. It isn’t binding, but it can be one of the most useful things a parent leaves behind.
Plan for Their Future, Starting Today.
One session to map how to protect your child’s benefits and their security for life.
Schedule Your Blueprint Session